What a ₹10 lakh MSME loan is meant for
A loan of this size usually funds working capital, stock, small machinery, shop or workshop upgrades, and early expansion for a micro or small enterprise. It sits at the top of the Mudra range and at the lower end of typical MSME term loans, which makes it the most commonly searched amount among small business owners.
The government's role is mainly to reduce risk for the lender through credit guarantee, so banks are more willing to lend without property security. The loan itself is still a commercial loan that must be repaid with interest.
Key Takeaways
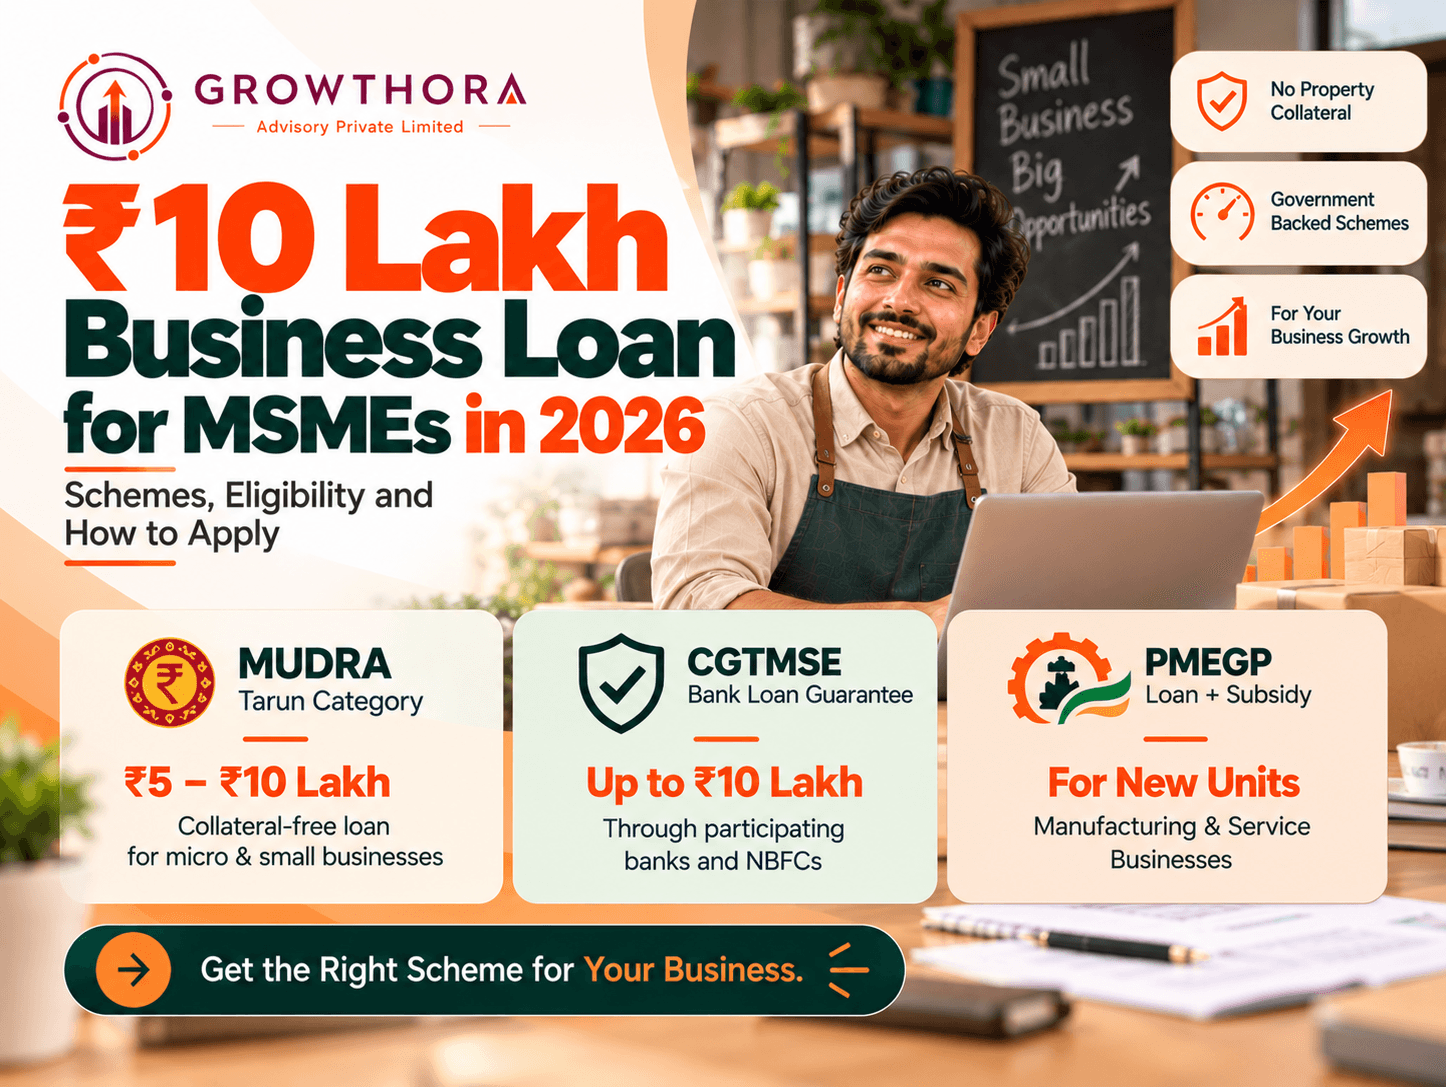
- Mudra Tarun is the main government route to a ₹10 lakh loan, covering ₹5 lakh to ₹10 lakh for non-farm micro and small businesses.
- Mudra loans are generally collateral-free because they are covered under a credit guarantee mechanism, but lenders still assess credit score and cash flow.
- The CGTMSE guarantee allows banks to lend collateral-free credit to eligible MSMEs, and lenders commonly extend collateral-free credit up to ₹10 lakh to micro enterprises.
- Udyam registration is the key MSME document and is free to obtain on the official Udyam portal.
- Interest rates are not fixed by the scheme and depend on the lender, your credit profile, and business vintage and tenure, so compare at least three offers.
- PMEGP is a different route for new manufacturing and service units that combines a loan with a government subsidy, and it suits first-time entrepreneurs better than a plain working capital loan.
Government-backed routes to a ₹10 lakh loan
| Route | How it works | Collateral |
|---|---|---|
| Mudra Tarun | Loans from ₹5 lakh to ₹10 lakh for non farm micro and small businesses through banks, small finance banks and NBFCs | Generally none |
| CGTMSE backed MSME loan | A bank lends to an eligible MSME and the credit guarantee trust covers a portion of the default risk | Collateral free for eligible borrowers, with a personal guarantee in some cases |
| PMEGP | Credit linked subsidy for new manufacturing and service units, with the bank providing the loan | As per bank norms, with a government subsidy on project cost |
| Stand Up India | Loans from ₹10 lakh to ₹1 crore for SC, ST and women entrepreneurs setting up greenfield enterprises | As per bank norms with guarantee support |
Eligibility criteria
- The business should be a micro or small enterprise in manufacturing, trading, or services, run as a proprietorship, partnership, LLP, or company.
- The applicant should be an Indian resident with a valid Udyam registration, PAN, and bank account.
- Most lenders prefer a business vintage of at least one year, though Mudra and new business schemes also finance start-ups.
- A good credit score and a clean repayment record on earlier loans improve approval chances and pricing.
- The business should not be in sectors excluded by the lender, and the loan must be for a genuine business purpose.
Documents required
- Identity and address proof such as Aadhaar and PAN of the proprietor, partners, or directors
- Udyam registration certificate and GST registration, where applicable
- Business proof such as a shop license, partnership deed, or certificate of incorporation
- Bank statements for the last 6 to 12 months and income tax returns where available
- A short business plan or project report with the purpose and amount of the loan
- Quotations for machinery or stock if the loan is for asset purchase
How to apply for a ₹10 lakh MSME loan
- Register your enterprise on the Udyam portal and keep GST, PAN, and bank details ready.
- Decide on the right route: Mudra Tarun for a simple loan or a CGTMSE-backed bank loan if you want a larger or structured facility.
- Apply through a bank branch, the Mudra portal, or a lender's online MSME loan page, and submit the documents.
- Complete KYC and credit assessment, which may include a visit to your business premises.
- Review the sanction letter for interest rate, tenure, processing fee, prepayment charges, and security terms before accepting.
- Receive the disbursal in your business account and use the funds only for the stated purpose.
Tips to improve your chances of approval
Keep business and personal finances separate, maintain regular bank inflows, and file GST and income tax returns on time. A clear one-page plan explaining what the money will be used for and how it will be repaid helps a credit officer say yes faster. Avoid applying to many lenders at once, since multiple credit inquiries can lower your score.
Frequently Asked Questions
Can an MSME get a ₹10 lakh loan without collateral?
Yes, Mudra Tarun loans up to ₹10 lakh and CGTMSE-backed MSME loans are generally offered without collateral, subject to the lender's credit assessment.
What is the Mudra Tarun category?
Tarun is the top Mudra category and covers loans from ₹5 lakh to ₹10 lakh for non farm micro and small enterprises.
Is Udyam registration mandatory for an MSME loan?
Udyam registration is not legally required for every loan, but lenders and government schemes increasingly ask for it as proof of MSME status, and it is free to obtain.
What interest rate will I pay on a ₹10 lakh MSME loan?
Rates are set by the lender and depend on your credit score, business vintage and tenure, so compare offers from banks, small finance banks and NBFCs before choosing.
How long does it take to get a ₹10 lakh business loan?
With complete documents, many lenders decide within a few days to a few weeks, while government scheme loans through banks can take longer depending on verification.
Can I get more than ₹10 lakh later?
Borrowers who repay Tarun loans on time may become eligible for higher limits under Tarun Plus, and larger MSME loans are available through bank credit with CGTMSE cover.
Want a ₹10 lakh MSME loan sanctioned faster?
A complete file with Udyam registration, clean bank statements, and a clear business plan gets approved sooner. Book a free consultation with Growthora, and we will prepare your documents, pick the right scheme, and coordinate with lenders on your behalf.
Next step
Apply this to your business.
Confirm whether this applies to your legal structure, industry classification, and credit history - in under 30 minutes with an advisor.