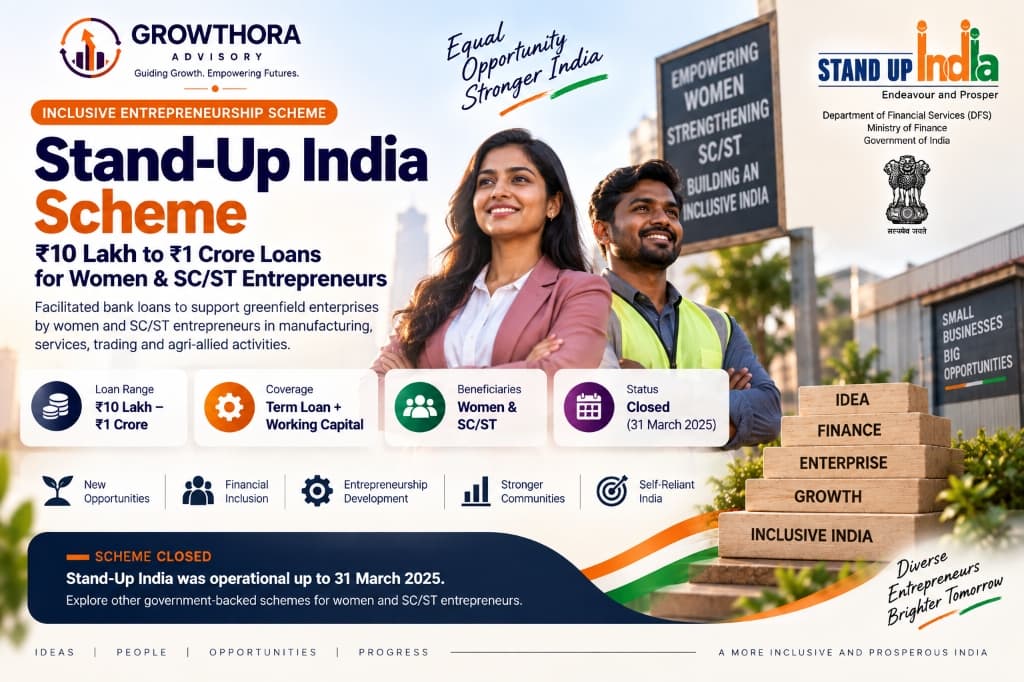
Stand-Up India Scheme – ₹10 Lakh to ₹1 Crore Loans for Women & SC/ST Entrepreneurs
Department of Financial Services (DFS), Ministry of Finance
Government entrepreneurship credit scheme that facilitated composite bank loans from ₹10 Lakh to ₹1 Crore for eligible women and SC/ST entrepreneurs to establish greenfield enterprises in manufacturing, services, trading and eligible agriculture-allied activities. The original Stand-Up India Scheme was operational up to 31 March 2025.
Who Can Apply?
Verified criteria and borrower eligibility guidelines set by the Government of India.
Women Entrepreneurs
Women entrepreneurs above 18 years of age were eligible to establish a new greenfield enterprise under the scheme.
SC / ST Entrepreneurs
Scheduled Caste and Scheduled Tribe entrepreneurs above 18 years of age were eligible for assistance for setting up qualifying greenfield enterprises.
Greenfield Enterprise
The enterprise had to be a first-time venture of the beneficiary in manufacturing, services, trading or eligible activities allied to agriculture.
Ownership Requirement
For non-individual enterprises, at least 51% of the shareholding and controlling stake had to be held by an eligible SC/ST or woman entrepreneur.
No Loan Default
The borrower was required not to be in default to any bank or financial institution.
Eligible Sectors
Eligible greenfield projects included manufacturing, services, trading and activities allied to agriculture.
Key Features
Core benefits, guarantees, and subsidy structures under this flagship program.
₹10 Lakh to ₹1 Crore Composite Loan
Scheduled Commercial Banks could provide composite loans between ₹10 Lakh and ₹1 Crore covering eligible term loan and working capital requirements.
Up to 85% of Project Cost
The composite loan could generally cover up to 85% of the project cost, subject to the beneficiary contribution and convergence support prescribed under the scheme.
Margin Money up to 15%
Margin money requirement was up to 15% of project cost and could be supported through convergence with eligible Central or State Government schemes. The borrower was required to contribute at least 10% of project cost from own funds.
Repayment up to 7 Years
The loan could be repaid over a period of up to 7 years, including a moratorium period of up to 18 months.
Competitive Interest Rate
The applicable interest rate was required to be the lowest applicable rate of the bank for the borrower category, subject to the ceiling prescribed under Stand-Up India guidelines.
Credit Guarantee Option
Banks could obtain eligible guarantee support under the Credit Guarantee Fund Scheme for Stand-Up India Loans, while collateral requirements remained subject to the lending bank's decision and applicable scheme norms.
Scheme Benefits
Application Process
Check Eligibility
The applicant had to qualify as an eligible woman or SC/ST entrepreneur and propose a qualifying greenfield enterprise.
Prepare Project Proposal
Prepare the project report, project cost estimates, business plan, financial projections and supporting documents required by the lending bank.
Apply Through Eligible Bank
Applications were submitted through Scheduled Commercial Banks and could also be initiated through the Stand-Up India or Jan Samarth digital ecosystem while the scheme was operational.
Bank Appraisal & Sanction
The lending bank independently evaluated the project's viability, repayment capacity, promoter contribution, security and applicable guarantee arrangements before sanctioning the loan.
Documents Required
Keep the following paperwork ready for instant verification and fast processing.
Frequently Asked Questions
Stand-Up India Closed – Explore Current Funding Options for Women & SC/ST Entrepreneurs
Get assistance with eligibility assessment, project report preparation and identification of currently available government-backed business funding schemes.