Main fast unsecured options compared
| Option | Typical speed | Key features |
|---|---|---|
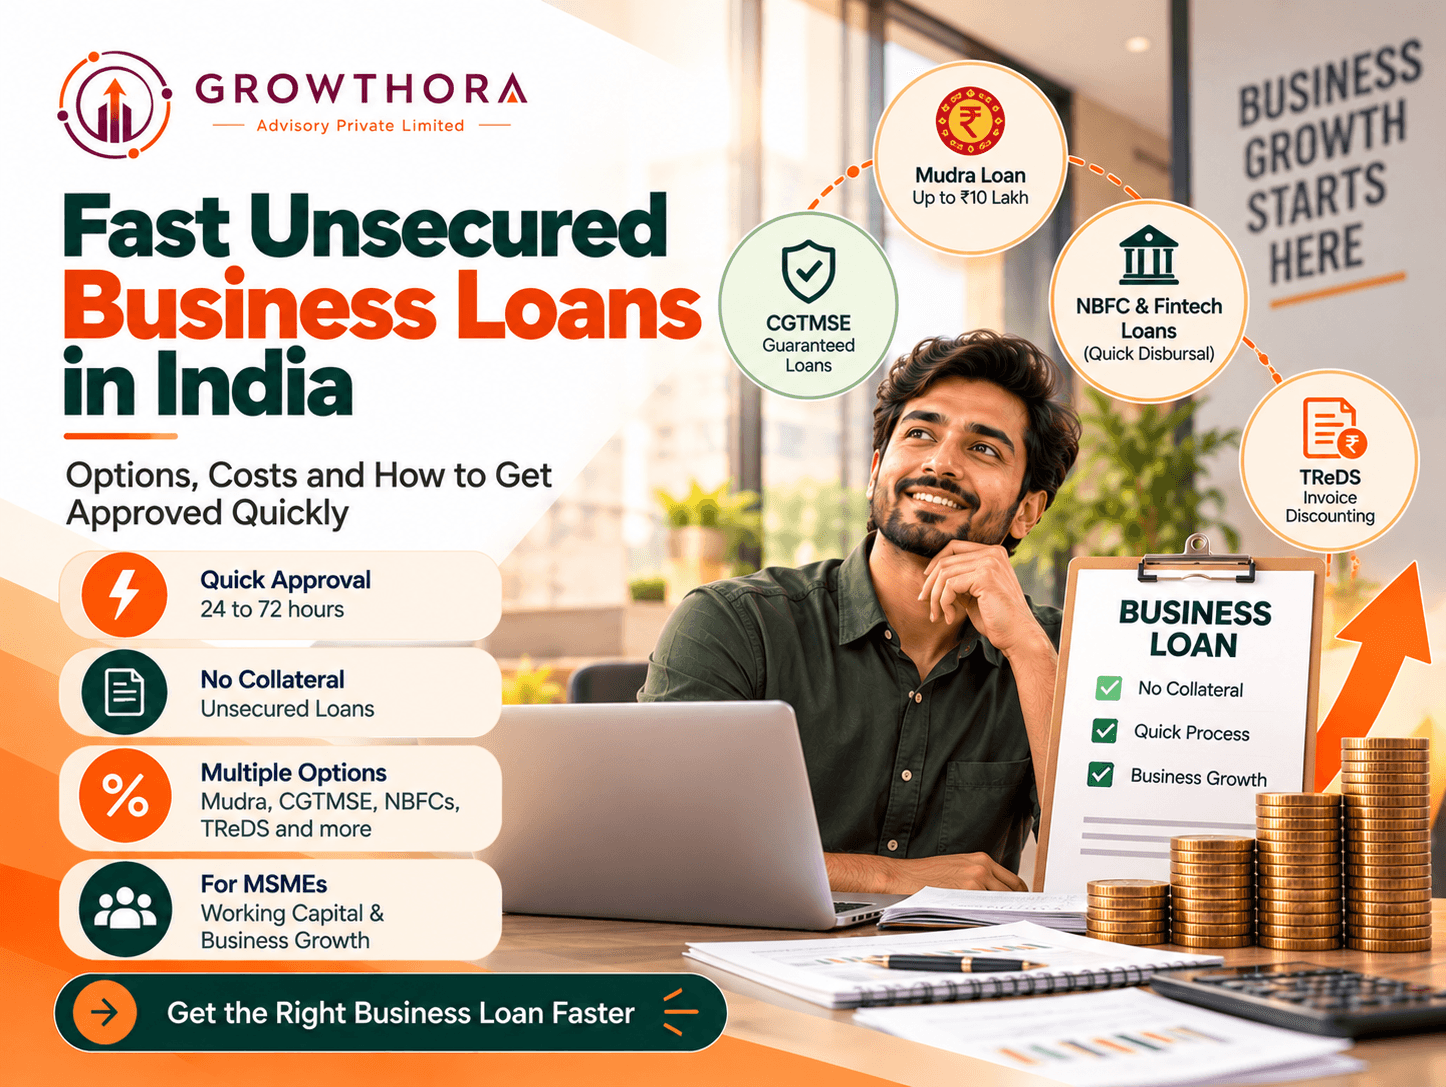
| Mudra loan (PMMY) | Days to weeks | Up to ₹10 lakh for micro and small businesses, generally collateral free through a credit guarantee, lower cost |
| CGTMSE backed bank loan | Days to weeks | Bank lends without collateral to eligible MSMEs under a government guarantee, larger limits possible |
| NBFC or fintech working capital loan | 24 to 72 hours | Digital process using GST and bank data, higher interest and fees, flexible tenure |
| Business overdraft or line of credit | Days | Pay interest only on the amount used, suits seasonal cash needs |
| Invoice discounting and TReDS | Same day to a few days | Cash against approved invoices from large buyers, priced by market bidding |
Key Takeaways
- Speed comes from clean documentation, a good credit score and digital data such as GST returns and bank statements, not from skipping checks.
- Government backed routes such as Mudra and CGTMSE give the cheapest collateral free credit, but they can take longer than private lenders.
- NBFCs and fintech lenders are fastest, but they usually charge higher interest and fees, so the annual percentage rate matters more than the headline rate.
- Invoice discounting through TReDS lets a supplier get cash against approved invoices from large buyers, often at lower cost than an unsecured loan.
- RBI's digital lending framework requires a key fact statement showing the APR and all charges, and funds should flow directly from the lender to your account.
- Fake loan apps and advance fee scams are common, so never pay a fee to receive a loan and always verify the lender's registration.
What makes a business loan unsecured
- An unsecured loan does not need property, machinery or stock pledged against it. The lender relies on your repayment capacity, credit history and business performance instead. Because the lender takes more risk, the interest rate is usually higher than on a secured loan and the loan amount is capped by your turnover and cash flow.
- For small businesses the main advantage is speed and simplicity. There is no valuation, legal search or mortgage registration, so approval can be completed in days
Eligibility lenders usually check
- Business vintage, often at least 6 to 12 months for fintech lenders and 1 to 3 years for banks
- A credit score of about 700 or above for the owner and the business
- Steady monthly bank credits and a clean statement without frequent bounces
- GST registration and regular GST returns, plus income tax returns where available
- A business that is not in an excluded sector, with a proper Udyam registration for MSME schemes
Documents that speed up approval
- PAN and Aadhaar of the proprietor, partners or directors
- Udyam registration, GST certificate and business proof
- Last 6 to 12 months of bank statements, with account aggregator consent if requested
- GST returns and income tax returns for the last year or two
- A short note on the purpose of the loan and expected repayment source
How much it really costs
- Look beyond the interest rate. Processing fees, documentation charges, GST on fees, prepayment penalties and late payment charges all raise the real cost. RBI's digital lending framework requires lenders to show a key fact statement with the annual percentage rate, which includes all charges, so compare offers on APR and total repayment, not on the monthly rate alone.
- With the repo rate raised to 5.50% on 7 October 2026 and the stance moved to calibrated tightening, floating rate and new unsecured loans are likely to be priced higher, so locking in a fair fixed rate and avoiding unnecessary borrowing both matter.
Steps to get a loan quickly and safely
- Check your credit score and clear small overdue amounts before applying.
- Keep Udyam, GST, PAN and bank records updated and consistent.
- Apply to two or three regulated lenders only, because many enquiries lower your score.
- Read the key fact statement, sanction letter and repayment schedule line by line.
- Confirm that money will be credited directly to your business account by the lender.
- Use the funds only for the stated purpose and set up auto debit to avoid late fees.
Red flags to avoid
- Any lender that asks for an advance fee, insurance charge or processing fee before disbursing
- Apps that demand access to your contacts, photos or messages
- Offers with no document check and guaranteed approval
- Lenders that cannot show their RBI registration or the bank or NBFC they partner with
- Unclear charges and no written key fact statement
Frequently Asked Questions
What is a fast unsecured business loan?
It is a business loan that needs no collateral and is usually approved within a few days based on credit score, bank statements, GST data and cash flow.
How quickly can I get an unsecured business loan in India?
Fintech and NBFC lenders can sanction within 24 to 72 hours with complete digital documents, while Mudra and CGTMSE backed bank loans can take days to weeks.
What interest rate do unsecured business loans carry?
Rates depend on the lender, your credit score and tenure, and unsecured loans cost more than secured ones, so compare the annual percentage rate and all fees before accepting.
Can a new business get an unsecured loan?
Yes, through Mudra, Stand Up India and some fintech products, though most private lenders prefer at least 6 to 12 months of business history.
Is invoice discounting a good alternative?
Yes, TReDS lets suppliers get cash against invoices accepted by large buyers, often at a lower cost than a general unsecured loan.
How do I spot a fake loan app?
Be careful if it asks for an upfront fee, demands access to your contacts, cannot show RBI registration or does not give a written key fact statement.
Need working capital quickly without the wrong loan?
The cheapest fast loan is the one matched to your documents and cash flow. Book a free consultation with Growthora and we will compare lenders, prepare your documents and help you secure a transparent unsecured business loan.
Next step
Apply this to your business.
Confirm whether this applies to your legal structure, industry classification, and credit history - in under 30 minutes with an advisor.