Key highlights: PMEGP second-loan limits and subsidy rates
| Parameter | Manufacturing | Service / Business |
|---|---|---|
| Maximum project cost eligible for subsidy | Up to ₹1 crore | Up to ₹25 lakh |
| Subsidy rate | 15% in most areas; 20% in NER and hill states | 15% in most areas; 20% in NER and hill states |
| Maximum subsidy in most areas | ₹15 lakh | ₹3.75 lakh |
| Maximum subsidy in NER and hill states | ₹20 lakh | ₹5 lakh |
| Beneficiary contribution | 10% of project cost | 10% of project cost |
| Remaining finance | Balance considered by bank as term loan, subject to appraisal | Balance considered by bank as term loan, subject to appraisal |
Important: If your proposed project cost exceeds the relevant subsidy ceiling, the excess amount may be considered by the bank without PMEGP margin money subsidy, subject to the bank's credit decision and applicable rules
PMEGP Second Loan: Get Up to ₹1 Crore with 15% to 20% Subsidy for Business Expansion
A business that has moved beyond its start-up stage may need new machinery, more production capacity, better technology or a larger workspace. If your existing unit was supported under PMEGP, REGP or MUDRA and has performed well, the second-loan component may help finance that next stage of growth.
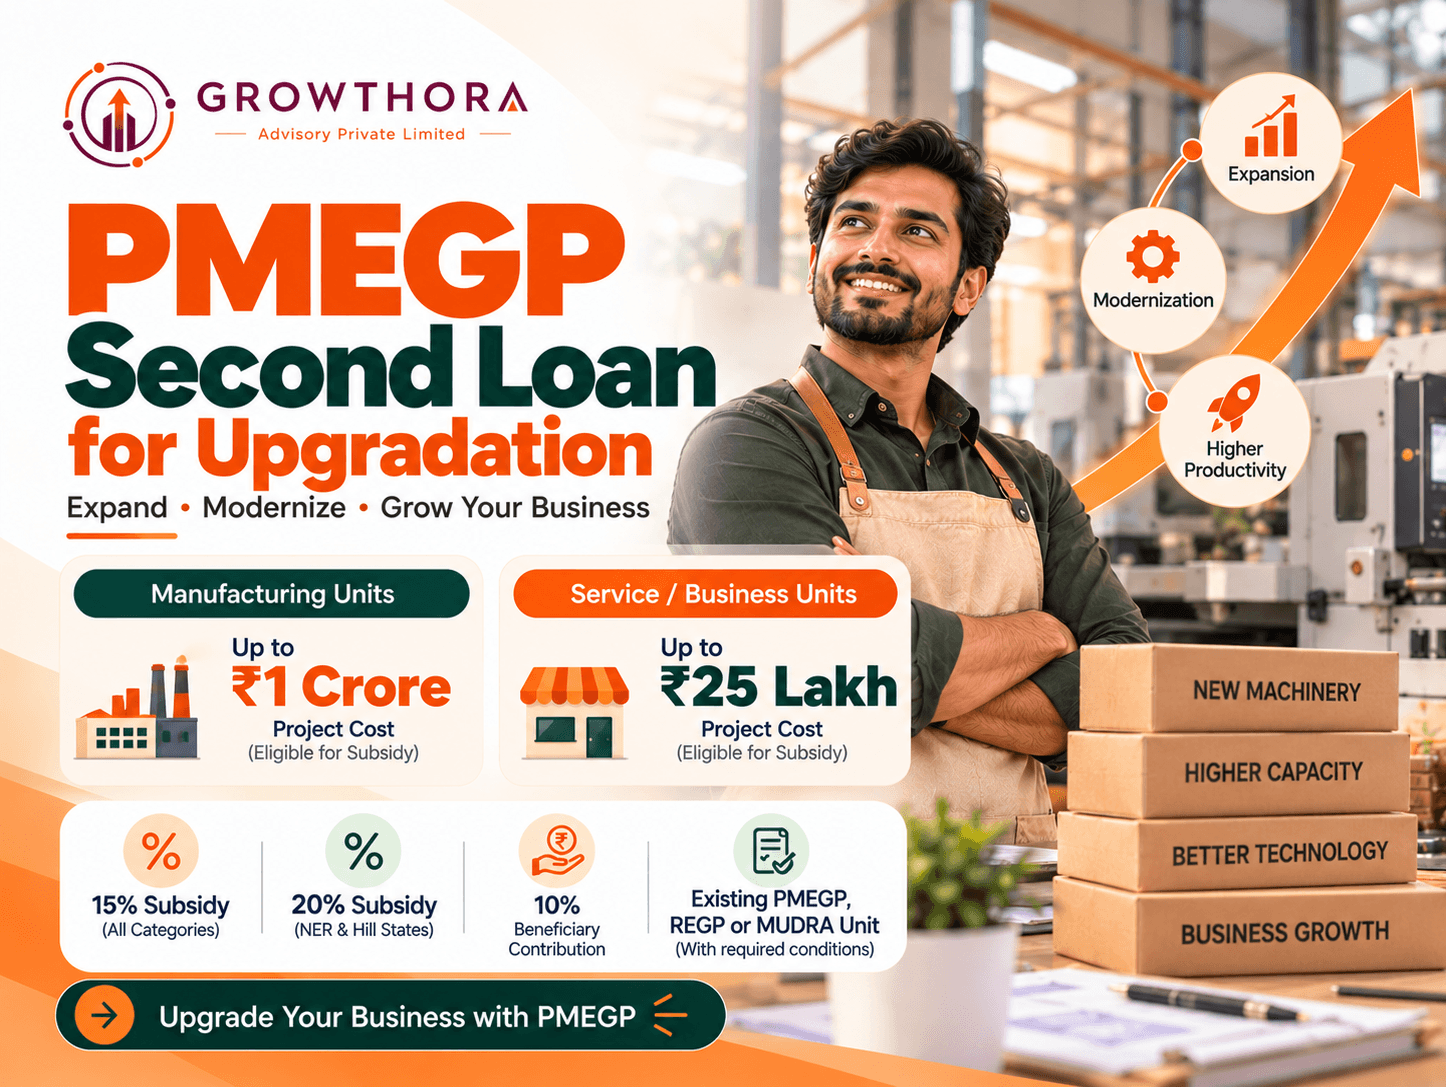
Under the applicable PMEGP upgradation guidelines, the maximum project cost eligible for margin money subsidy is ₹1 crore for manufacturing and ₹25 lakh for service or business activities. The subsidy rate is 15% for all categories and 20% in the North Eastern Region and hill states. The beneficiary contribution is 10% of the proposed project cost. These are scheme limits, not a promise that every applicant will receive the maximum amount. The bank still assesses the project and decides whether to sanction credit.
This guide explains PMEGP second loan eligibility, subsidy calculations, documents, the application route and common mistakes to avoid.
Quick answer: What is the PMEGP second loan for upgradation?
The PMEGP second loan for upgradation is a financial assistance option for eligible existing PMEGP, REGP or MUDRA units that want to expand, modernize or improve productivity. The eligible project-cost ceiling for subsidy is ₹1 crore for manufacturing and ₹25 lakh for service/business units. The subsidy is 15%, or 20% in the North Eastern Region and hill states, with a 10% beneficiary contribution. The first loan must meet the scheme's repayment conditions, the margin money subsidy adjustment condition must be satisfied, the unit should have been profitable for the last three years, and Udyam registration is mandatory. Final approval depends on eligibility checks and bank appraisal.
Who can apply for a PMEGP second loan?
The second-loan facility is intended for existing units that want to upgrade or expand, rather than for a completely new business idea. The official PMEGP portal states that eligible existing units financed under PMEGP or MUDRA may apply where the first loan has been repaid within the stipulated time, the margin money claim has been adjusted, the unit has made a profit for the last three years and Udyam registration is in place. The scheme guidelines also refer to existing REGP units.
Existing PMEGP, REGP or MUDRA-supported unit: Check that your original finance and subsidy records match the applicable scheme rules.
Repayment history: The first loan should have been repaid within the stipulated schedule. Obtain a repayment or closure statement from the lender.
Profitability: Be ready to demonstrate that the unit has been profitable for the last three years using reliable financial records.
Margin money adjustment: The first loan's margin money subsidy must have completed the prescribed verification and adjustment process.
Udyam registration: Registration on the Udyam portal is mandatory for this upgradation facility.
A credible expansion plan: Your proposal should explain what will change, why the investment is needed and how it is expected to improve output, productivity, quality or employment.
The exact supporting records may vary with the lender and implementing agency. GST returns, ITRs, audited statements, bank statements and other statutory records may be requested during scrutiny, but applicants should confirm the current checklist instead of assuming every document is a universal scheme condition.
What can the second loan be used for?
The second loan is designed to support modernization and growth of an existing eligible unit. Depending on the approved project and bank appraisal, proposed investment may include:
- Purchase and installation of new machinery or production equipment.
- Automation or technology upgrades that improve productivity.
- Expansion of manufacturing capacity or service delivery capability.
- Improvements to the existing unit's fixed assets, including eligible building-related works where permitted.
- Equipment that supports improved quality, efficiency, output or additional employment.
Prepare a clear item-wise cost estimate. Machinery quotations, installation costs, layout details and a practical explanation of the expected business benefit can make the proposal easier to assess. Do not assume that every working-capital expense or general business cost will automatically qualify under the upgradation component.
How much PMEGP 2nd loan subsidy can you receive?
The subsidy is calculated as a percentage of the eligible project cost, subject to the sector-specific ceiling. It is not a flat cash payment that is automatically transferred to the business owner.
Example 1: Manufacturing project of ₹60 lakh
Assuming the entire ₹60 lakh project cost is accepted as eligible for the upgradation subsidy, a 10% beneficiary contribution would be ₹6 lakh. At a 15% subsidy rate, the indicative margin money subsidy would be ₹9 lakh. The remaining ₹45 lakh would be the balance to be considered by the bank, subject to its appraisal and the applicable subsidy handling process.
Example 2: Manufacturing project of ₹1 crore
At the maximum manufacturing project-cost ceiling, a 10% contribution is ₹10 lakh. The subsidy would be ₹15 lakh in most areas, or ₹20 lakh in the North Eastern Region and hill states. The balance amount is considered by the bank. These figures illustrate the scheme formula only and do not predict a loan sanction.
Example 3: Service project of ₹20 lakh
For an eligible service/business project of ₹20 lakh, the beneficiary contribution at 10% would be ₹2 lakh. The indicative subsidy would be ₹3 lakh at 15%, or ₹4 lakh at 20% in the eligible regions. The balance would be considered by the bank.
In all examples, the subsidy is subject to eligibility, eligible cost verification, required checks and the prescribed lock-in and adjustment process. Confirm the final calculation with the implementing agency and financing bank before making purchase or repayment decisions.
Documents to prepare before applying
- Use this as a preparation checklist, then confirm the current portal and bank requirements for your case.
- Udyam Registration certificate.
- First-loan sanction details and loan account statement.
- Proof of repayment or closure showing repayment within the stipulated schedule.
- Record or confirmation that the first margin money subsidy has been adjusted as required.
- Financial statements for the last three years and supporting profit records.
- Income tax returns and GST returns, where applicable or requested.
- Recent bank statements and details of existing loans or liabilities.
- A fresh Detailed Project Report (DPR) describing the upgrade, cost, implementation plan, projected sales and expected employment impact.
- Machinery or equipment quotations and installation estimates.
- Business registration, ownership, lease or premises documents, as relevant.
- Any additional forms, declarations or certificates requested by the implementing agency or bank.
How to apply for a second loan under PMEGP
- Review your eligibility first. Check the original scheme, repayment record, margin money adjustment, three-year profitability and Udyam registration.
- Prepare a realistic expansion DPR. Explain the current business, the reason for expansion, proposed machinery or technology, total project cost, expected output, market demand and repayment capacity.
- Collect the supporting documents. Use the current checklist from the official PMEGP portal and the agency handling your application. Do not rely on an old checklist copied from another website.
- Submit the application through the official PMEGP online facility for upgradation, following the options currently available on the portal. If you need help locating the correct application route, contact the nearest implementing agency.
- The implementing agency conducts preliminary scrutiny and forwards eligible applications to a financing bank. The bank assesses the proposal on technical and financial grounds and makes the credit decision.
- Respond promptly to clarification requests. Keep copies of the submitted application, DPR, quotations and acknowledgements.
- After sanction, follow the bank's disbursement conditions and the scheme's subsidy verification, lock-in and adjustment process. Do not treat the subsidy as immediately available cash.
Can you apply to a different bank for the second loan?
The official PMEGP portal says an eligible beneficiary may apply to the same bank that provided the first loan or to another bank willing to extend the credit facility. A new lender will still conduct its own appraisal and may ask for repayment records, financial statements and details of existing liabilities. Before switching banks, ask both the current lender and proposed lender what documents and account-closure evidence they need.
Is a second PMEGP loan guaranteed after repaying the first loan?
No. Repaying the first loan is an important eligibility condition, but it does not guarantee approval. The unit must also meet the other scheme conditions, and the bank will assess the viability of the proposed upgrade, the business's financial position, repayment capacity and the documents submitted. A well-prepared DPR can explain the investment clearly, but it cannot replace eligibility checks or the bank's credit decision.
Common mistakes that can weaken an application
- Using an old project report without explaining the new investment or business need.
- Quoting inflated machinery prices or submitting incomplete quotations.
- Showing optimistic revenue growth without explaining customer demand, capacity or operating costs.
- Ignoring existing loans, overdue liabilities or the cash needed to operate after expansion.
- Assuming that the full maximum subsidy will be approved automatically.
- Treating the subsidy as an upfront grant instead of following the prescribed verification and adjustment process.
- Submitting inconsistent figures across the DPR, ITRs, GST records, bank statements and quotations.
A strong application should be easy to verify. Keep the figures consistent, explain assumptions and show how the proposed upgrade will improve the business's ability to repay the loan.
How a project report consultant can help
A project report consultant can help organize the expansion plan, estimate project costs, build financial projections and prepare a DPR that answers the questions a lender is likely to ask. For an existing business, the report should connect past performance with the proposed investment. It should explain why the new machinery or capacity is needed, how much additional revenue is reasonably expected, what expenses will rise and whether projected cash flow can support repayments.
Growthora Advisory can be considered for support with project-report preparation and funding documentation. Before engaging any consultant, confirm the scope of work, fees, deliverables, revision policy and whether the service includes coordination with the bank or implementing agency. No consultant can guarantee subsidy approval or loan sanction.
Need help preparing an expansion DPR? Explore PMEGP loan consultant support
For scheme-specific background, also read the [PMEGP scheme guide](https://www.growthora.co.in/schemes/pmegp) and the Growthora article on [PMEGP subsidy and eligibility](https://growthora.co.in/blog/pmegp-scheme-2026-subsidy-and-eligibility). Verify these internal URLs are live and canonical before publishing.
Frequently asked questions
What is the maximum PMEGP second loan for manufacturing?
The maximum project cost eligible for margin money subsidy under the upgradation component is ₹1 crore for manufacturing. The bank makes its own credit decision, and any amount above the subsidy ceiling may be considered without PMEGP subsidy under applicable rules.
What is the PMEGP second loan limit for service businesses?
The maximum project cost eligible for margin money subsidy for service or business activities is ₹25 lakh. The subsidy rate is 15%, or 20% in the North Eastern Region and hill states, subject to eligibility.
What is the PMEGP 2nd loan subsidy rate?
The applicable rate is 15% of eligible project cost for all categories, increasing to 20% in the North Eastern Region and hill states. The maximum subsidy is ₹15 lakh for manufacturing and ₹3.75 lakh for service/business in most areas, with higher ceilings of ₹20 lakh and ₹5 lakh respectively in the specified regions.
Who is eligible for a PMEGP second loan?
Eligible existing PMEGP, REGP or MUDRA units may apply if they meet the applicable conditions, including timely repayment of the first loan, adjustment of the first margin money subsidy, profitability over the last three years and mandatory Udyam registration.
Do I need to repay the first PMEGP loan before applying?
The official portal says the first loan should have been repaid within the stipulated time. Keep the repayment or closure evidence ready and confirm your account status with the financing bank.
Can a MUDRA loan holder apply for PMEGP upgradation assistance?
The second-loan component includes eligible existing MUDRA units as well as PMEGP and REGP units. Eligibility and the required records should be confirmed with the official portal and implementing agency.
Can I apply through a different bank?
The official PMEGP portal says the beneficiary may apply to the original financing bank or another bank willing to extend credit, subject to that bank's appraisal.
Is subsidy paid directly to my bank account?
Do not assume it is paid as immediate cash. PMEGP margin money subsidy follows a prescribed verification, lock-in and loan-account adjustment process. Confirm the current procedure with the implementing agency and bank.
Are three years of GST returns compulsory?
The official summary of the second-loan conditions specifically refers to profitability over the last three years and mandatory Udyam registration. GST returns may be requested where applicable or by the bank, but check the current document list rather than treating three years of GST filings as a universal standalone rule.
Does a consultant guarantee approval?
No. A consultant may help prepare the DPR and organize documentation, but the implementing agency verifies eligibility and the bank decides whether to sanction credit. Approval or subsidy cannot be guaranteed.
Official sources and further reading
Revised PMEGP Scheme Guidelines: Open the official guideline PDF
PMEGP official portal: Open PMEGP portal
Ministry of MSME: Open ministry website
Scheme details and application procedures can change. The official portal and current guidelines should take precedence over summaries on third-party websites.
Publishing and technical SEO checklist
- Replace author and reviewer placeholders with real names, relevant credentials and an accurate biography. Do not publish an unverified CA or financial-advisor byline.
- Replace schema image and date placeholders with the real public featured-image URL and actual publication or modification dates.
- Verify all internal links, especially /schemes/pmegp, /services/pmegp-loan-consultant and the related PMEGP blog article, return a successful page and are canonical.
- Use one clear H1, descriptive H2/H3 headings, a concise answer near the top, useful tables and FAQs that are visible on the page.
- Add a relevant original featured image with descriptive alt text. Avoid decorative stock images that do not explain the topic.
- Ensure the page is indexable, has a self-referencing canonical URL, works on mobile, loads quickly and is linked from the PMEGP hub and relevant related articles.
- Validate JSON-LD syntax and structured data with Schema.org Validator and Google's current testing tools. Structured data does not guarantee a rich result or AI Overview inclusion.
- Keep FAQ content visible and consistent with the FAQ schema. Google limits FAQ rich results in many cases, so do not publish schema solely to promise enhanced search display.
- Review the scheme facts whenever official PMEGP guidance changes. Update the visible last-updated date only after a genuine review.
Next step
Apply this to your business.
Confirm whether this applies to your legal structure, industry classification, and credit history - in under 30 minutes with an advisor.